· ReadyStack
Worked example
Real numbers from this tool, line by line.
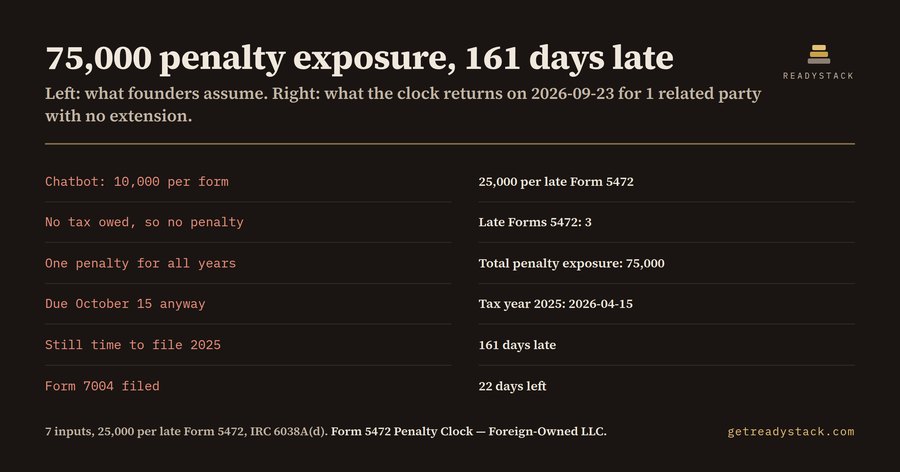
A foreign-owned US LLC that skipped Form 5472 for tax years 2023, 2024 and 2025 is carrying $75,000 of IRS penalty exposure today, 2026-09-23 — and the 2025 form is already 161 days late. If you are a non-US founder with a single-member Delaware or Wyoming LLC, this is for you.
The filing nobody told you about
A single-member LLC owned by one foreign person is a disregarded entity. It usually owes no US income tax, so many founders assume there is nothing to file. Since 2017 that has been wrong. The Treasury regulations treat a foreign-owned disregarded entity as a corporation for one purpose: Form 5472. For every tax year in which the LLC had a reportable transaction with its foreign owner or another foreign related party, it must mail a pro forma Form 1120 with Form 5472 attached. Reportable transactions include the owner funding the LLC, paying its formation fees, or taking money out.
What a missed form costs
IRC 6038A(d) sets the penalty at 25,000 for each failure to file Form 5472 when due. It is per form, one per foreign related party per tax year, regardless of tax owed. If the IRS mails a notice and the failure continues more than 90 days after that notice, another 25,000 is added for each 30-day period or part of one. The IRS instructions state there is no maximum.
The due date is the 15th day of the 4th month after year-end: April 15 for a calendar-year LLC. A Form 7004 extension moves it to October 15. That is the whole difference between these two results the clock returns for the same founder on 2026-09-23:
- No extension filed: Late Forms 5472: 3. Total penalty exposure: $75,000. Tax year 2025: 2026-04-15, 161 days late.
- Form 7004 filed (October 15): 2 late forms, $50,000, and 22 days left to file 2025 on time.
Why the usual free answers miss it
A general tax calculator asks for income and tax. A disregarded LLC with no US income returns 0, so it shows no risk at all. Chatbots often quote 10,000, the amount before the 2017 tax act raised it to 25,000 for tax years starting in 2018, or they describe a single penalty rather than one per form per year. They also assume an October date that needs Form 7004.
How the clock counts
The tool takes 7 inputs: the first tax year with a reportable transaction, the latest tax year to check, the number of foreign related parties, whether a Form 7004 extension was filed, the check date, the date of an IRS notice if you have one, and how many forms that notice names. Each year's form counts as late once the check date passes its due date (weekends roll to Monday). Late forms are multiplied by 25,000. If a notice date is entered, it counts the 30-day periods after notice plus 90 days and multiplies by 25,000 per named form.
A harder case: two foreign related parties, tax years 2024 and 2025, and an IRS notice dated 2026-05-11 naming both 2025 forms. On 2026-09-23 the clock shows 4 late forms, $100,000 in initial penalties, 2 continuation periods, another $100,000, and $200,000 total exposure.
What to do with the number
The count is not a bill; the IRS decides penalties and can accept a reasonable-cause statement. It tells you which years to file first. Flat-fee CPA services advertise one Form 5472 with the pro forma 1120 at $399 per year, which is small next to 25,000 per form. The whole calculation is free in the browser extension and on the web page, with no key. A one-time key adds a .csv export of the year-by-year schedule for your CPA and a reminder before each April 15 or October 15.
Sources: IRC 6038A(d); IRS Instructions for Form 5472 (12/2024).
Questions people ask
What does the Form 5472 Penalty Clock actually calculate?
It counts how many Forms 5472 a foreign-owned US LLC has missed, one per foreign related party per tax year, and multiplies by the 25,000 IRS penalty under IRC 6038A(d). It adds 25,000 for each 30-day period that runs more than 90 days after an IRS notice, and shows each year's April 15 or October 15 due date with the days late or left.
Who is the Form 5472 Penalty Clock for?
Non-US founders who own a single-member Delaware, Wyoming or other US LLC, such as ecommerce sellers, SaaS founders and freelancers who formed through a filing agent. The LLC is a disregarded entity, owes no US income tax, and still must mail a pro forma Form 1120 with Form 5472 for every year it had a reportable transaction with its owner.
Why not just ask a chatbot or use a free tax calculator?
General tax calculators assume a tax is owed, so they show zero for a disregarded LLC with no US income. Chatbots often quote the old 10,000 penalty that TCJA raised to 25,000 in 2018, and they miss that the penalty is per form per year and that a Form 7004 extension moves the due date to October 15.
What is free and what does the paid key add?
The whole calculation is free in the popup and on the web page, with no key, no limit and no watermark: late forms, penalty per year, continuation periods after a notice, and the next due date. The one-time 29 key adds a .csv export of the year-by-year schedule for your CPA and a browser reminder before each due date.
How much does a person charge to file Form 5472?
Flat-fee CPA services advertise one Form 5472 with the pro forma Form 1120 at 399 per tax year (form5472.online, September 2026), and larger firms quote after a review. That is the cost of filing on time; the IRS penalty for each form that is late or missing is 25,000, which is why knowing the count first matters.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.